Insight
Combining ILC and GENIUS Act applications
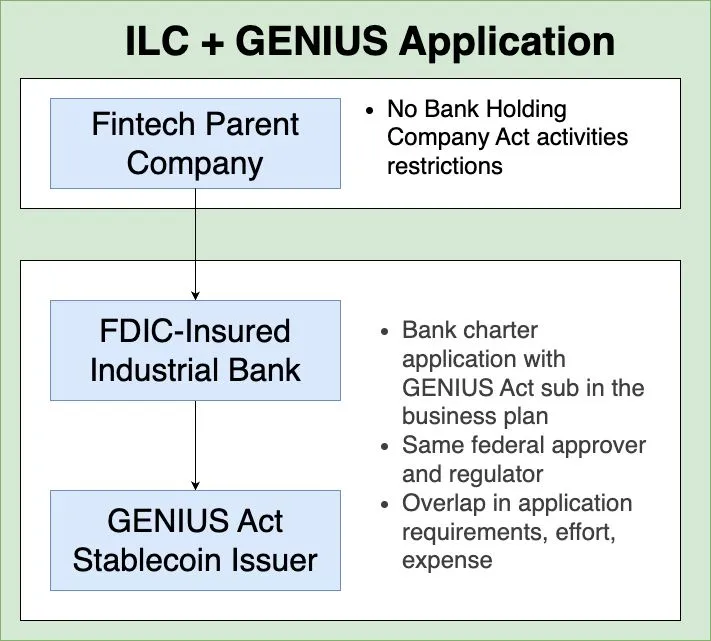
Combining ILC and GENIUS Act applications is an intriguing possibility for a fintech looking to break out of the sponsor-bank paradigm. In this scenario, the company applies for a new ILC charter whose business plan includes a subsidiary issuer. The federal approver and regulator for both applications would be the FDIC.
The approach has pluses and minuses. On one hand, the ILC and its subsidiary would enjoy:
✅ Nationwide deposit-taking and lending powers with the ability to export home state interest rates;
✅ Full credit and debit card issuance and acquiring capabilities;
✅ Eligibility for Federal Reserve master account access as a Tier 1 institution (subject to the special rules on ILC overdrafts);
✅ Unlimited stablecoin issuance capacity without mandatory transition thresholds;
✅ Nationwide money transmission and custody powers when operating through the issuer subsidiary; and
✅ Freedom from Bank Holding Company Act restrictions on nonfinancial activities.
On the other hand, the structure has major downsides that make it unattractive as a pure-play stablecoin strategy:
⚠️ Timeline: Even in a favorable environment, an ILC charter typically takes 18-24 months from application to opening.
⚠️ Investment: Compared to uninsured options, an insured bank application requires higher initial capital and upfront investment in professional services, management, and systems.
⚠️ Getting Approved: The FDIC has historically applied heightened scrutiny to ILC applications and, while this suspicion may be easing, ILC policy is still evolving.
⚠️ Ongoing Regulation: As an insured institution, an ILC faces comprehensive banking regulation, including wide-ranging supervision and affiliate transaction restrictions.
In short, this approach only makes sense if stablecoin issuance is part of a broader financial services strategy. But if a company wants an ILC for other reasons, the incremental effort of throwing in a GENIUS Act application is probably minimal.