Insight
Stablecoin sandwich as an alternative to MTLs
As fintechs work on GENIUS Act stablecoin strategies, one thing is becoming clear: The Act offers the equivalent of a national money transmission license for many previously non-crypto use cases. It could come to displace the traditional state money transmission licenses for many fintechs.
This realization has partly sunk in with the trade associations and advocacy organizations that wrote Congress last week requesting repeal of the GENIUS Act's Section 16(d), which grants nationwide money transmitter powers to state depository institutions that own permitted payment stablecoin issuers.
But the truth is, Section 16(d) is mostly a state-bank parity provision. That's because the federal issuer licenses would enable many companies to perform the activities for which they currently hold state MTLs, but with just one national license.
It does not matter that the GENIUS Act limits issuers to stablecoin activities. The "stablecoin sandwich" -- an established pattern in pre-GENIUS Act stablecoin services -- provides the same utility as money transmission in many use cases. In a stablecoin sandwich, the sender gives the service provider national currency, which is exchanged into stablecoins upon receipt, then back to national currency when it comes time to pay the recipient. (Unless, of course, the recipient prefers to receive stablecoins.)
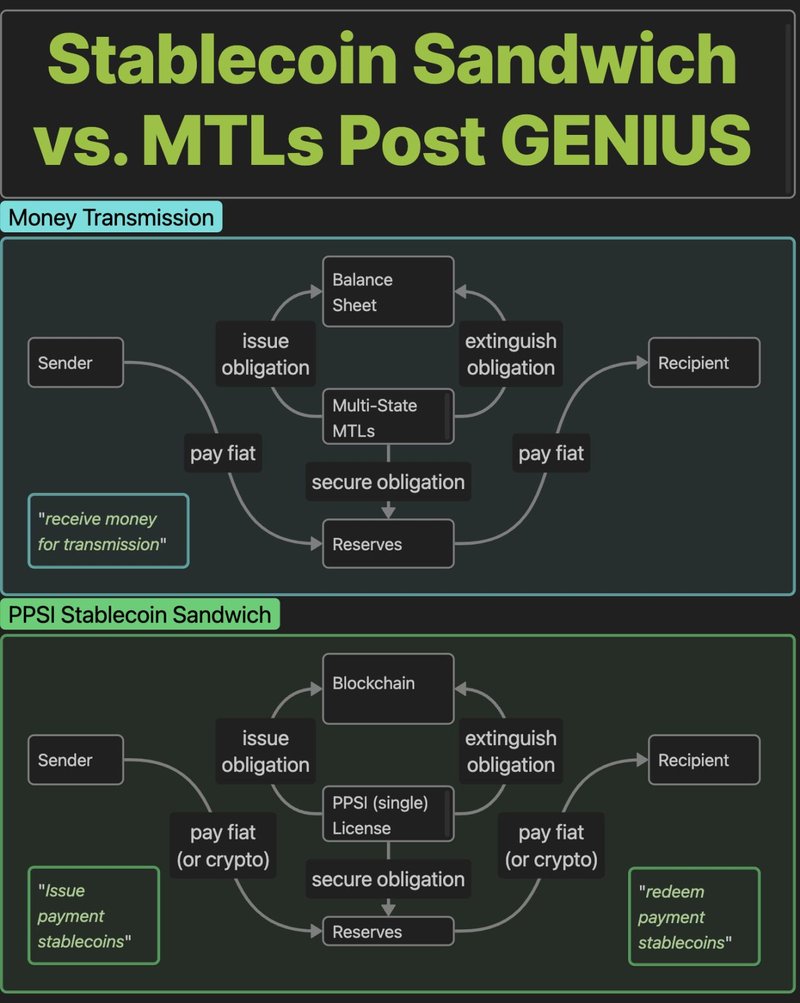
The stablecoin sandwich is enabled under the GENIUS Act by issuers' core powers to "issue payment stablecoins" and "redeem payment stablecoins." Moreover, as my crude diagram shows, it's just a minor variation on the traditional money transmission model. Both models have the service provider accepting money from the sender, issuing an obligation, and holding reserves against that obligation until the recipient is paid. The difference is that the money transmitter issues the obligations in the form of liabilities on its balance sheet, while the payment stablecoin issuer issues them in the form of stablecoins on a blockchain.
This raises an obvious question for any fintech that has MTLs or needs them: If you can accomplish the same business goals with one national license instead of 40+ state licenses, why stick with state licenses?