Insight
The path to large state-regulated stablecoin issuers
A common misconception is that the GENIUS Act allows only sub-$10b issuers to be state-qualified and imposes federal regulation on all larger issuers. Neither is true.
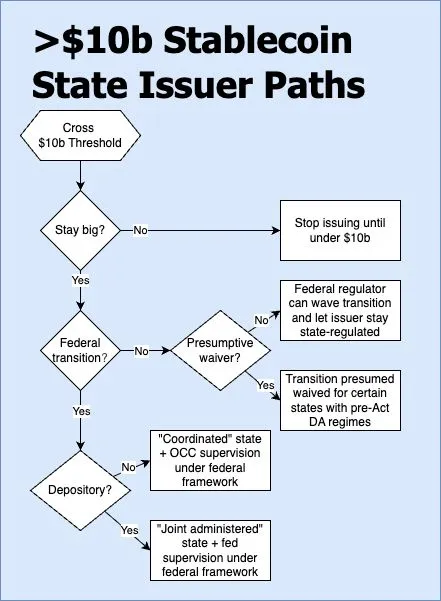
For a state issuer that reaches the threshold, the default path is transition to hybrid supervision, under the federal framework, by both a state and a federal regulator. The state issuer doesn't have to convert to a federal charter unless it wants to.
The hybrid framework has some odd quirks: Nonbank issuers transition to supervision administered by the state and OCC "acting in coordination." Meanwhile, (uninsured) depository institutions get supervision that is "jointly administered" by the state regulator and the institution's "primary Federal payment stablecoin regulator" (though it's a little unclear who that is.)
There is also a way to avoid federal regulation altogether. The "applicable federal regulator" can waive the transition to the federal framework and let the issuer continue under state-only supervision, based on a fairly constrained set of factors.
This waiver may be very easy for certain issuers to get. That's because it is presumed approved if the state had a pre-GENIUS digital assets framework, has approved at least one stablecoin issuer under that framework, and is now federally certified under the Act.
Note the law doesn't say the issuer itself has to be approved before the cut-off date -- only that the state had a framework in place. The presumption is reversible only upon clear and convincing evidence of inadequacy or systemic risk.
It's not exactly clear how the presumptive waiver provision is going to be applied -- or even which of the states will be eligible. One thing is clear though: There are several paths for new stablecoin issuers to grow as large as they want without ever becoming federally qualified -- and maybe even avoid federal regulation altogether.